Your Home Is Worth More Than Any Appraisal Can Tell You — Here's How to See It
Every few years, someone in a suit walks through your house with a clipboard and tells you what it's worth. They measure the square footage, note the number of bathrooms, compare your place to three similar homes that sold nearby, and hand you a number.
And that number matters — for refinancing, for insurance, for estate planning. No argument there.
But here's what the appraisal doesn't capture: the stability that let you take a career risk because your housing costs were fixed. The health dividend of having a safe, consistent place to sleep every night for a decade. The way your kids' childhoods were shaped by the neighborhood you chose. The equity in your relationships with neighbors who would show up for you in a hard moment.
None of that fits on a form. But all of it is real — and all of it matters to the actual return on your homeownership investment.
The Limits of Market-Price Thinking
Real estate investing culture tends to reduce everything to numbers: price per square foot, cap rates, appreciation percentages, cash-on-cash returns. These are genuinely useful tools when you're making decisions about investment properties.
But when that same purely financial lens gets applied to your primary residence — the place where you live your actual life — it starts to distort the picture in ways that can lead you toward bad decisions.
You might sell a home that's serving your family beautifully because the market is hot and the math looks good on paper. You might under-invest in improvements that would significantly enhance your daily quality of life because the ROI isn't strong enough on a spreadsheet. You might spend years anxiously tracking your Zestimate instead of just... living in your house.
The market price of your home is one data point. It's not the whole story.
Stability as a Financial Asset
Let's start with something that's actually quantifiable, even if it rarely gets quantified: the financial value of housing stability.
When your monthly housing cost is fixed — as it is with a 30-year mortgage — you're insulated from the rent inflation that renters face every time their lease comes up. Over a decade, in most US markets, that protection compounds significantly. The renter who was paying $1,800 a month in 2015 might be paying $2,600 or more for the same unit today. Your mortgage payment? Unchanged.
Beyond that, housing stability creates a platform for other financial decisions. It's easier to build an emergency fund, invest consistently, and take career risks when your housing cost is predictable. The homeowner who took a chance on a startup or went back to school while their mortgage stayed flat — that's a real return that never shows up in appreciation figures.
Health Returns: Underrated and Underestimated
The research on housing stability and health outcomes is pretty striking. Stable homeownership is associated with lower rates of chronic stress, better sleep, and stronger mental health outcomes — particularly for children. The mechanism isn't complicated: when you're not worried about where you're going to live, your nervous system gets to relax in ways that have genuine physiological effects.
For families, this plays out in childhood development metrics, school performance, and long-term social outcomes. For adults, it shows up in reduced cortisol levels, better cardiovascular health, and lower rates of anxiety disorders.
Now, nobody's suggesting you should stay in a house that doesn't work for your life because of abstract health statistics. But when you're doing the math on whether to sell and rent for a while, or whether a move makes financial sense, the health cost of destabilizing a stable living situation deserves a line item.
The Legacy Dimension
This one is harder to quantify but impossible to ignore if you're thinking long-term.
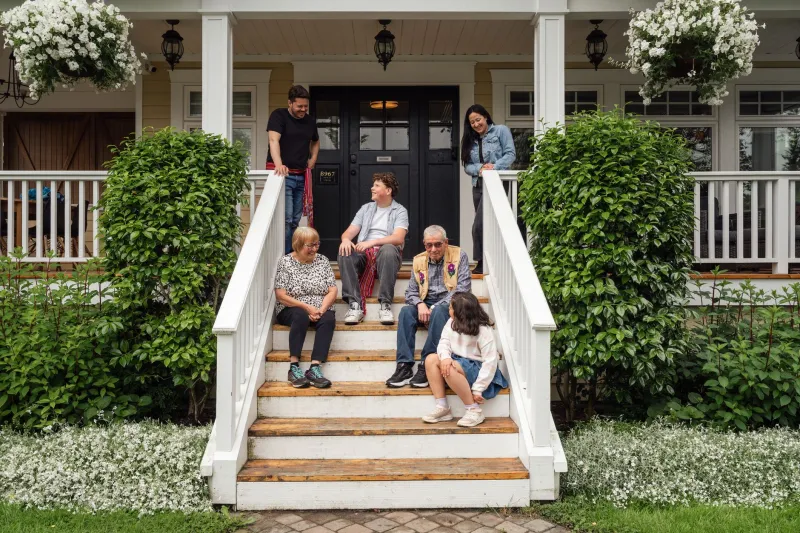
A home held over decades becomes something more than a financial asset — it becomes a family anchor. The house where holidays happened, where kids grew up, where parents aged in place. The ability to pass that on — either as a physical property or as the accumulated wealth that comes from decades of equity building — is a form of intergenerational wealth transfer that the appraisal absolutely cannot measure.
For many American families, homeownership is still the most accessible path to meaningful wealth accumulation. Not because home prices always go up (they don't, not everywhere, not always), but because the forced savings mechanism of a mortgage, combined with leverage and time, tends to build equity in ways that are genuinely difficult to replicate through renting and investing the difference.
The legacy value of a home isn't just financial, either. There's something real about a place that holds family history — and the option to either preserve that or convert it to capital is a form of wealth that liquid assets don't offer.
Opportunity Cost: What Your Home Enables
Here's a dimension of home value that almost never gets discussed: the opportunity cost your home absorbs on your behalf.
A well-located home in a strong school district means you're not paying private school tuition. A home with a functional home office means you're not paying for coworking space. A home with a good guest room means you're not booking hotels when family visits. A home with outdoor space means you're getting recreation value you'd otherwise have to pay for elsewhere.
These aren't trivial amounts. Private school tuition alone can run $15,000 to $40,000 per year per child in many US cities. Coworking memberships run $200 to $500 a month. Hotel stays for family visits add up fast. When you start adding up what your home is replacing, the picture of its value gets a lot richer.
How to Actually Use This Framework
So what do you do with all of this? A few practical applications:
When deciding whether to improve or move: Run the full value calculation, not just the ROI on the renovation. If an improvement significantly enhances your daily quality of life, your kids' experience at home, or your family's health and stability — that matters even if it doesn't add dollar-for-dollar to your resale value.
When evaluating a potential sale: Don't just ask what you'll net from the transaction. Ask what you'll be giving up in stability, community, school continuity, and the compounding effects of staying put. Sometimes the math still clearly favors selling. But sometimes it doesn't — and you'd never know if you only looked at the market price.
When thinking about where to invest your home improvement dollars: Prioritize improvements that serve your actual daily life first, and resale considerations second. A home that works beautifully for the people living in it tends to be well-maintained, well-loved, and genuinely attractive to future buyers anyway.
The Whole Picture
Your home is a financial asset. That's real, and it matters. But it's also a health asset, a stability asset, a legacy asset, and a platform for the life you're actually trying to build.
The smartest homeowners we know aren't the ones obsessively tracking their home's market value. They're the ones who understand the full range of returns their home is generating — and make decisions accordingly.
That's not a soft, sentimental way of thinking about real estate. It's actually the most rigorous way there is.